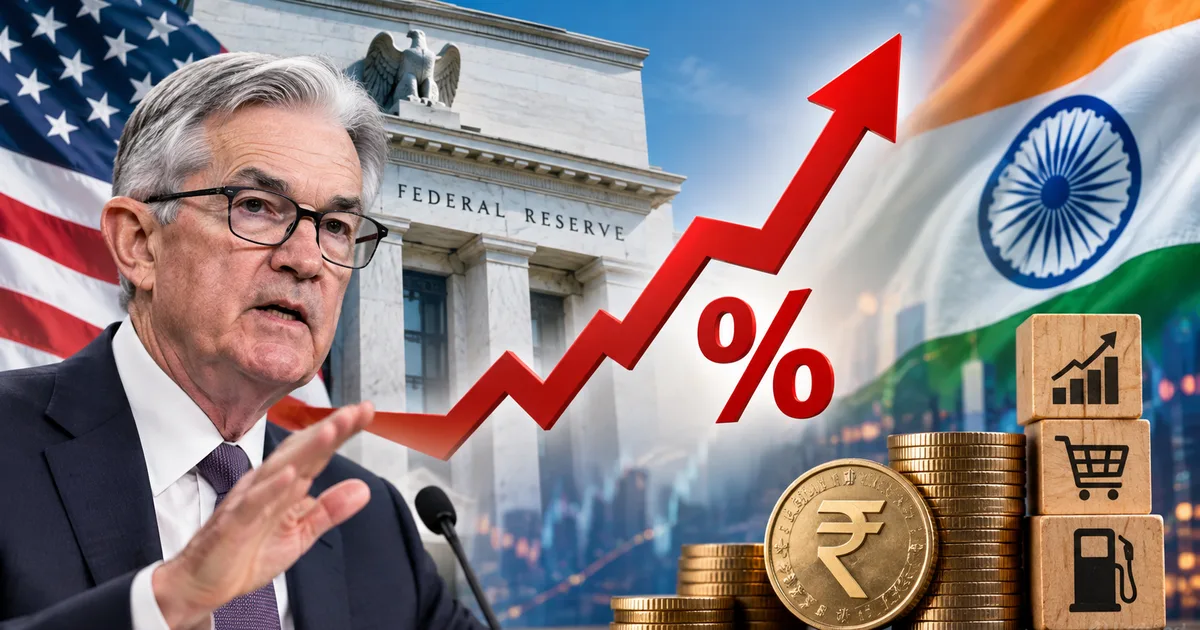
If you're wondering about the US Fed rate hike September 2026 impact on India, you're in the right place. Last night, the US Federal Reserve, led by Chair Kevin Warsh, pulled the trigger on a 25 basis point rate hike. Imagine waking up in Mumbai and seeing that a group of bankers sitting 13,000 kilometres away in Washington just made your home loan more expensive. Honestly, it sounds absurd. But that's exactly how the global economy works right now. This decision is going to ripple through our stock markets and the value of the rupee in your wallet. It'll also hit the tech sector's hiring plans. And eventually, it changes the EMI you pay for your house or car.
I know financial news is absolute alphabet soup. FPIs and basis points. Bond yields and hawkish pivots. (Annoying, I know). We're going to cut through all of that noise. We'll look at exactly what happened in Washington and how it directly affects your hard-earned money back home.
Why did the US Fed raise rates again?
To understand the September 2026 hike, you've got to look at inflation in the United States. Prices there are still going up way too fast. For the last three years, the Fed had paused their rate hikes, leaving the rate sitting at 3.5% to 3.75% since July 2023. Markets had gotten comfortable. Everyone thought the next move would be a rate cut.
But things changed fast.
August US consumer price index (CPI) numbers came in hot, rising 3.4% from a year earlier. And global crude oil prices are a mess again. Brent crude briefly crossed $108 a barrel recently. Higher oil prices mean higher transport costs. That means your groceries get more expensive. Your Amazon deliveries get more expensive too.
So Kevin Warsh and the Federal Open Market Committee (FOMC) decided they had to act. They raised rates by a quarter of a percentage point. But here's the part that really made the markets nervous. They updated their "dot plot". That's a chart showing where Fed officials think interest rates are heading over the next few years.
The median projection for the end of 2026 was raised to 4.1%. I think that tells us they're planning at least one more rate hike before the year ends. And they pushed up their projections for 2027 and 2028 as well, to 4.1% and 3.9% respectively. They completely dropped their old language about inflation being a supply shock issue. Now they admit this is a persistent demand problem.
How this hits the Indian stock market
If you've got money in mutual funds or direct stocks, you probably woke up to a sea of red on your trading app today. Look, the immediate reaction to a US rate hike is rarely positive for emerging markets like India. The Asian-Pacific markets saw a very cautious open. Dalal Street felt the heat immediately.
Here's how the math works. The US 10-year Treasury yield briefly crossed 5% this week. That's the return you get for lending money to the US government. It is a massive number. US government bonds are considered the safest investments on the planet. When global investors can get a guaranteed 5% return in the US without taking risks, they start pulling their money out of India.
We call this Foreign Portfolio Investment (FPI) outflow. When FPIs sell Indian shares to take their dollars back home, the Sensex and Nifty naturally take a hit. They prefer the safety of US bonds over the volatility of Indian equities.
But it isn't all doom and gloom. A decade ago, a 5% US bond yield would've caused an absolute panic in the Indian markets. Today, the Indian market has a massive shock absorber. Retail investors like you and me.
Domestic support is very strong right now. We have monthly Systematic Investment Plan (SIP) inflows consistently exceeding Rs 22,000 crore. All that domestic money coming in every month cushions the blow when foreign investors decide to sell. We aren't entirely at the mercy of foreign capital anymore. (Which makes sense, actually, given how many people started investing recently). If you want to read more about how global financial shifts are playing out locally, check our analysis on the BRICS Currency Payment System 2026.
The rupee continues to struggle
The currency market is where things get a bit stressful. The Indian rupee has been under severe pressure lately. It is hovering near 96 to the US dollar. That's a tough number to look at if you've got kids studying abroad or if you're planning an international trip. It's also bad if you run a business that imports raw materials.
When the US Fed raises rates, the dollar gets stronger against almost every other currency. Higher rates in the US attract global capital. That drives up demand for the dollar. At the same time, India is dealing with its own macroeconomic headaches. Oil prices are high. Since India imports more than 80% of its oil requirements, we have to pay for it in dollars. More expensive oil means we need more dollars. That just weakens the rupee even more.
The Reserve Bank of India (RBI) is actively managing this situation. They've been intervening heavily through state-owned banks to prevent the rupee from falling too fast. If you ask me, defending the currency has its limits. I'm not sure exactly how long they can keep it up. India's forex reserves are strong, which gives the RBI the ammunition it needs to fight this volatility. But spending billions of dollars just to keep the exchange rate stable isn't a permanent fix.
Will your home loan EMI increase?
This is the question most people actually care about.
The US Fed raised rates. But does that mean your HDFC or SBI home loan is going to cost more next month? The short answer is no. Probably not next month. But don't expect your EMI to go down anytime soon either.
The RBI sets the repo rate in India. That is the rate at which they lend to commercial banks. While the RBI doesn't blindly follow the US Fed, they can't ignore them entirely. If the interest rate gap between the US and India gets too narrow, money flows out of India even faster.
India's 10-year government bond is currently yielding above 7.09%. The spread still favours Indian debt. But as US yields rise, that relative advantage shrinks. Investors demand higher compensation for taking on the currency risk of investing in India. Plus, domestic inflation in India accelerated to 4.82% in August. The RBI has its hands full trying to manage local prices.
"The RBI will likely keep domestic rates elevated for longer, pushing any rate-cut cycle into Q2 or Q3 of 2026 to impact consumption and capex sentiment," noted Seema Srivastava, Senior Research Analyst at SMC Global Securities.
Basically, if you were hoping for a rate cut this Diwali to lower your monthly outflow, you need to recalibrate your expectations. The RBI will hold rates steady for a much longer period. If you're on a floating rate home loan, your EMI is going to stay high well into late 2026. For more background on how these macro policies affect daily tech and finance, check out our Explainers section.
What this means for the tech sector and gold
High interest rates are tough on the technology sector. Startups rely on cheap venture capital funding to grow rapidly. When interest rates are at 4%, venture capitalists become much more demanding. They want to see actual profits instead of just user growth. The exact numbers are a bit fuzzy, but we might see Indian tech startups tightening their belts even further. If you're working in the IT sector, this rate regime means companies will remain cautious about hiring and expansion. We cover these industry shifts constantly in our Latest Tech News section.
Then there's gold. Indians love gold, both as jewellery and as an investment. But gold doesn't pay interest. When US Treasury bonds start paying close to 5%, investors often dump gold to buy bonds. Following the Fed announcement, global gold prices fell more than 1%.
Thing is, in India, because the rupee is weakening against the dollar, the local price of gold might not fall as sharply as the international price. The currency depreciation works as a strange buffer for domestic gold prices.
A silver lining for banking stocks
It is always interesting to see which sectors benefit when macroeconomic winds change. A rate hike is generally negative for equities. But the banking sector sometimes finds a strange kind of support here.
Anuj Gupta, a SEBI Registered Research Analyst, explained that while the 25-basis-point hike is broadly negative for the near term, higher rates can actually support the banking sector. How? Because it improves their lending yields and net interest margins. In my experience, banks are always quick to pass on higher interest rates to borrowers by raising your home loan EMI. They are way slower to help out depositors by raising your fixed deposit returns. (Which is super frustrating for savers).
So, large private and public sector banks might weather this storm a bit better than the rest of the market. Growth sectors and highly valued midcaps might still face some pressure from the global risk-off sentiment.
What you should do now
When global financial news gets this sketchy, the best thing an everyday investor can do is avoid panic. We've seen US rate hike cycles before. Yes, rates staying higher for longer is a shift from what markets expected six months ago. The US Treasury yield crossing 5% is a big deal for the world economy.
But the Indian economy of 2026 is very different from a decade ago. The domestic liquidity from retail investors gives the market a floor that didn't exist in the past.
Here are a few practical steps you can take right now:
- Keep your SIPs running. Don't stop your investments just because the market is reacting to Kevin Warsh in Washington. Market corrections are historically good times to accumulate units at lower prices.
- If you've got a home loan, try to make part-prepayments whenever you get a bonus or extra cash. Since rates are staying high, reducing your principal is the smartest guaranteed return you can get right now.
- Avoid locking into very long-term fixed deposits just yet. If the RBI eventually has to hike rates to defend the rupee, you might get slightly better FD rates in a few months. Keep your investments relatively liquid.
- Review your portfolio's exposure to rate-sensitive sectors. Understand that the days of easy, cheap money driving up valuations of unprofitable companies are suspended for the foreseeable future.
The global economy is complicated. The US Fed decisions definitely cast a long shadow over India. We're seeing that with the rupee sitting at 96 and foreign funds selling off. But understanding the mechanics behind these moves gives you a massive advantage.
You don't have to predict the next Fed move. You just have to make sure your own financial house is prepared for whatever they decide to do next.